Lending and Alternative Credit: A Complete Guide to Financial Technology in 2026
A complete 2026 guide to lending and alternative credit, covering BNPL, embedded lending, AI underwriting, revenue-based financing, risks, and regulation.
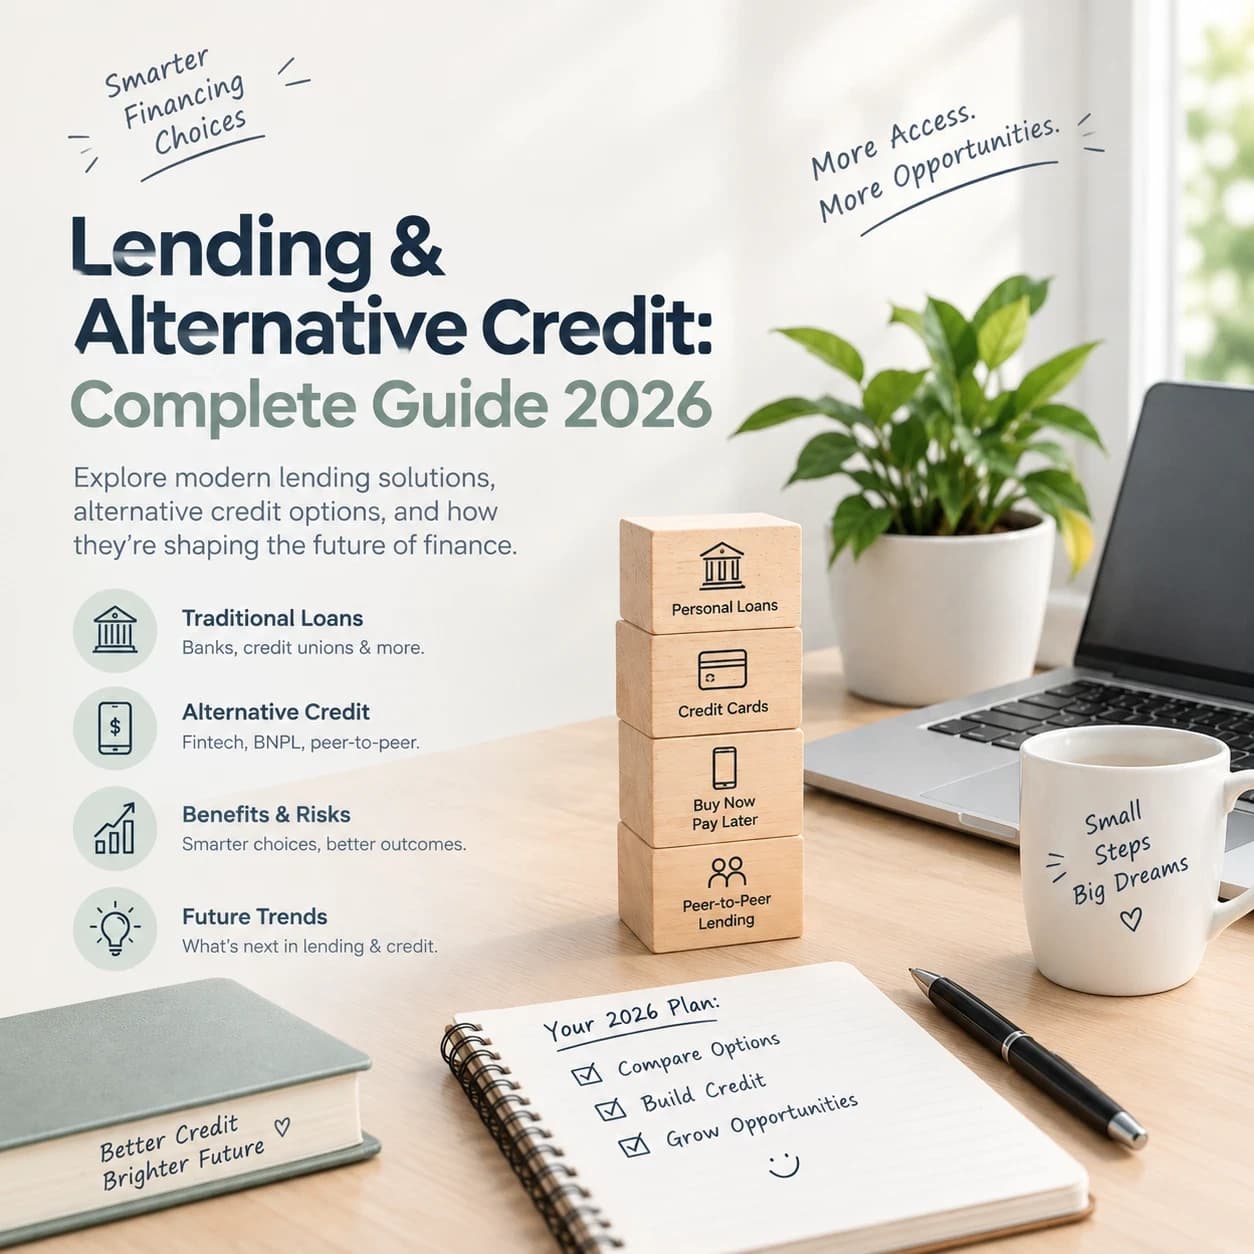
Lending and Alternative Credit: A Complete Guide to Financial Technology in 2026
Borrowing money used to follow a predictable, often frustrating path. A person or business would visit a bank, hand over a stack of paperwork, and wait days or weeks for a decision built almost entirely around a single number, a credit score. That process shut out millions of creditworthy people and businesses simply because their financial history did not fit neatly into a traditional model.
Fintech lending and alternative credit rebuilt that process from the ground up. Today, a small business can receive funding based on its actual daily sales, a shopper can split a purchase into four payments at checkout, and an AI model can approve a personal loan using thousands of data points in under a second. This guide explains what lending and alternative credit actually mean, why this shift matters so much, and walks through every major branch of the space, from peer to peer lending and buy now pay later to embedded credit, alternative data underwriting, and the private capital now fueling the entire industry.
What Are Lending and Alternative Credit
Lending and alternative credit refer to any method of extending money to a borrower using technology, data, or a business model that departs from the traditional bank loan process. This includes online personal loans, small business financing built on transaction data rather than years of tax returns, installment payment options at checkout, and credit products built entirely on alternative data sources instead of a traditional credit score.
The word alternative does not mean risky or informal. It means the underwriting process, the funding source, or the delivery method looks different from a conventional bank loan. A loan funded by individual investors instead of a bank, a credit decision based on a small business's real time sales data instead of a personal credit history, and a four payment installment plan offered at online checkout are all forms of alternative credit, even though each works in a completely different way.
Why Lending and Alternative Credit Matter
This shift matters because it solves problems that the traditional lending system left unresolved for a very long time.
It reaches people traditional lenders overlook: Millions of people and small businesses have thin or nonexistent credit histories, not because they manage money poorly, but because they are young, new to a country, or simply do not use the type of credit that traditional scoring models were built around. Alternative data and AI driven underwriting can evaluate creditworthiness using a far wider range of information, extending responsible credit to people a traditional bank would have automatically declined.
It speeds up decisions dramatically: A loan decision that once took days or weeks can now happen in seconds, since automated underwriting models can evaluate an application against thousands of data points almost instantly, compared to the far narrower set of factors a traditional credit file provides.
It fills gaps left by traditional banks: As many traditional banks have pulled back from smaller, riskier loans because they are less profitable to service manually, nonbank lenders and alternative credit platforms have stepped in to fill that gap, keeping credit available to small businesses and individuals who would otherwise be left without options.
It gives businesses more flexible ways to grow: Revenue based financing, invoice factoring, and merchant cash advances let a business access capital based on its actual sales performance rather than requiring collateral or a lengthy approval process, which matters enormously for seasonal or fast growing businesses that cannot wait weeks for funding.
It creates real accountability pressure: As AI underwriting has scaled rapidly, regulators have begun scrutinizing these models closely for fairness and transparency, which is pushing the entire industry toward more explainable, auditable credit decisions rather than opaque, unaccountable algorithms.
A Brief History of Lending Technology
Automated credit scoring itself is not new. The FICO score, still widely used today, was introduced in the late 1980s to standardize how lenders evaluated risk. What changed the trajectory of the industry was the internet, which made it possible to apply for credit entirely online, followed by the 2008 financial crisis, which caused many traditional banks to sharply tighten lending standards and pull back from smaller loans.
Peer to peer lending platforms emerged shortly after, connecting individual borrowers directly with individual investors willing to fund their loans, bypassing the traditional bank balance sheet entirely. Through the 2010s, a wave of online lenders built increasingly sophisticated underwriting models using alternative data, while buy now pay later services began embedding short term credit directly into online checkout experiences, particularly among younger shoppers.
By the 2020s, artificial intelligence had moved from an experimental underwriting tool into a core part of how most digital lenders evaluate risk, and institutional and private capital increasingly replaced individual investors as the primary funding source behind most large alternative lending platforms. Now, in 2026, the global alternative lending market has grown into a several hundred billion dollar industry, and the competitive focus has shifted from simply lending faster to lending more intelligently, using richer data and more precise risk models.
The Core Branches of Lending and Alternative Credit
Alternative credit is best understood as a collection of distinct models, each solving a different funding problem for a different type of borrower.
Peer to Peer and Marketplace Lending
Peer to peer lending platforms connect individual borrowers directly with individual or institutional investors who fund the loan, rather than relying on a bank's own balance sheet. The platform handles underwriting, servicing, and payment collection, while investors earn a return based on the interest paid by borrowers. Over time, many of these platforms have shifted from relying mainly on individual retail investors toward larger institutional funding sources, which has allowed them to scale far beyond their original size while keeping the same basic direct lending model.
Online Personal Loans
Digital personal loan providers allow a borrower to apply, receive a decision, and get funded entirely online, often within the same day. These lenders typically use a combination of traditional credit data and additional financial information, such as bank account activity, to make faster and sometimes more accurate lending decisions than a traditional bank relying on a credit score alone.
Buy Now Pay Later
Buy now pay later services let a shopper split a purchase into several installments, often interest free, directly at online or in store checkout. This has become one of the most visible forms of alternative credit, expanding rapidly across retail and ecommerce worldwide. The industry is increasingly consolidating around large retail and digital wallet ecosystems, with major platforms shifting from single provider partnerships toward offering shoppers a choice of several buy now pay later options at checkout. As adoption has grown, regulators in a number of markets have begun applying stronger consumer protection rules to these products, treating them more like traditional credit than a lightly regulated checkout feature.
Small Business and SME Lending
Small business lending platforms provide financing based on a business's actual operating data, including bank transaction history, payment processing volume, and accounting records, rather than requiring years of tax returns and physical collateral. This branch has grown quickly because traditional banks often find very small business loans unprofitable to underwrite manually, leaving a meaningful funding gap that platform based lenders have stepped in to fill using automated, data driven decision making.
Revenue Based Financing
Revenue based financing provides a business with upfront capital in exchange for a fixed percentage of future revenue until the amount is repaid, rather than a fixed monthly loan payment. This structure aligns repayment with how a business is actually performing, since payments naturally decrease during slower periods and increase during stronger ones, making it particularly attractive to seasonal or early stage businesses with variable income.
Invoice Factoring and Financing
Invoice factoring allows a business to receive immediate cash for unpaid customer invoices, rather than waiting the typical thirty to ninety days for a customer to pay. A financing provider advances most of the invoice value upfront, in exchange for a fee, and collects the full payment once the customer eventually pays. This has become an increasingly digital, fast moving product, with modern platforms able to verify and fund an invoice within a day rather than the multi week process traditional invoice financing once required.
Merchant Cash Advances
Merchant cash advances provide a business with upfront funding in exchange for a fixed portion of future card sales, collected automatically as a percentage of daily transactions. This product is particularly common among retail and restaurant businesses with strong daily card sales volume but limited traditional collateral, since the repayment structure is based directly on the business's own payment processing activity rather than a separate credit evaluation process.
Earned Wage Access
Earned wage access lets an employee access wages they have already earned before their official payday, typically for a small fee or at no cost at all, rather than turning to a high cost payday loan to cover an unexpected expense. This has grown rapidly as an employer offered benefit, and it directly targets one of the most damaging forms of traditional short term credit by giving workers access to money that is genuinely already theirs.
Credit Builder Products
Credit builder loans and secured credit cards are designed specifically to help someone with limited or no credit history establish a track record of on time payments, gradually building a stronger credit profile over time. These products are structured so that even a person who cannot yet qualify for traditional credit can begin building the history needed to access it in the future, often through very small, low risk loan amounts reported directly to credit bureaus.
Embedded Lending
Embedded lending places a credit offer directly inside a non financial app or platform at the exact moment a customer needs it, such as a financing option shown during an online checkout or a working capital offer presented directly inside a small business's point of sale system. This has become one of the fastest growing areas of alternative credit, since it removes the need for a borrower to separately search for and apply to a lender, instead meeting the borrowing need at the precise point where it naturally arises.
Decentralized Finance Lending
Decentralized finance lending platforms allow people to borrow and lend cryptocurrency directly through blockchain based smart contracts, without a traditional financial institution acting as an intermediary. Borrowers typically must provide collateral in the form of other digital assets, and interest rates are often set automatically based on real time supply and demand within the platform, rather than being determined by a traditional lender's own risk assessment process.
Microfinance and Financial Inclusion Lending
Microfinance platforms provide very small loans, often to entrepreneurs and individuals in developing economies who have no access to traditional banking at all. Digital delivery has dramatically lowered the cost of offering these small loans, since a mobile based platform can reach a borrower directly without the overhead of a physical branch, making it economically viable to serve borrowers that traditional microfinance institutions once struggled to reach profitably.
The Technology Powering Modern Lending
Several underlying technologies show up repeatedly across nearly every branch of alternative credit described above.
Alternative data underwriting: evaluates creditworthiness using information beyond a traditional credit file, including bank transaction history, payment processing data, and other digital financial footprints, allowing lenders to responsibly extend credit to people a traditional credit score alone would have excluded.
Artificial intelligence and machine learning: now sit at the center of most modern underwriting, capable of analyzing far more data points per applicant than a traditional manual review ever could, while also detecting fraud and predicting repayment risk with increasing precision.
Application programming interfaces: allow lending platforms to connect directly to a borrower's bank accounts, accounting software, or payment processor, pulling real, verified financial data automatically rather than relying on documents a borrower uploads and a human reviewer manually checks.
Open banking connections: let a lender securely view a borrower's real transaction history directly from their bank, with the borrower's consent, replacing outdated methods such as requiring uploaded bank statements that could be altered or were simply slower to obtain and review.
Funding the Lending Industry
Behind every alternative lending platform sits a source of capital that actually funds the loans being made. Increasingly, that capital comes from institutional investors and private credit funds rather than individual retail investors, drawn by the returns available in a sector that traditional banks have partly retreated from. This institutionalization has allowed many alternative lending platforms to scale dramatically, since large, stable sources of capital can support far more lending volume than the individual investor model that powered many early peer to peer platforms.
Regulation of Alternative Credit
Alternative credit sits under significant and increasing regulatory attention, covering fair lending requirements, interest rate limits, and growing scrutiny of how AI models make credit decisions. Regulators in several markets have taken direct enforcement action against lenders whose AI underwriting models produced unintentionally discriminatory outcomes, signaling that automated decision making does not exempt a lender from the same fair lending obligations that have always applied to traditional credit decisions.
Buy now pay later products have faced similarly increasing regulatory attention, as their rapid growth has pushed regulators to apply many of the same consumer protection standards used for traditional credit cards and installment loans, rather than treating them as a separate, lightly regulated category.
Challenges and Risks in Alternative Credit
The rapid growth of alternative lending has not eliminated every risk. Algorithmic bias remains a genuine concern, since an AI model trained on historical data can unintentionally learn and repeat past patterns of unfair lending if it is not carefully designed, tested, and monitored. Overextension of credit is a particular risk with products like buy now pay later, where a shopper can accumulate several simultaneous installment obligations across different providers without any single lender seeing the full picture. Funding concentration creates risk when a lending platform depends heavily on a small number of institutional investors, since a pullback in that funding can disrupt lending far more suddenly than a traditional bank's more diversified deposit base. Transparency and explainability remain an ongoing challenge, since both regulators and borrowers increasingly expect a clear, understandable reason behind an automated credit decision rather than an opaque algorithmic outcome.
The Future of Lending and Alternative Credit in 2026 and Beyond
Several clear themes are shaping the next phase of the industry. Artificial intelligence is moving from a competitive advantage into standard operating infrastructure, with lenders under growing pressure to make their models explainable and auditable rather than simply accurate. Buy now pay later is consolidating into larger retail and digital wallet ecosystems, shifting from a standalone product into one option among several embedded directly at checkout. Embedded credit continues to expand into new industries, meeting borrowers at the exact point of need rather than requiring a separate loan application process. And institutional capital continues to flow into the sector, giving alternative lenders the scale to compete directly with traditional banks across an increasingly wide range of loan types.
At the same time, the fundamentals of responsible lending have not changed. Credit still needs to be extended fairly, priced honestly, and repaid sustainably, and the lenders succeeding in 2026 are the ones building genuine improvements on those fundamentals rather than simply moving faster than everyone else.
Final Thoughts
Lending and alternative credit have moved from a narrow, one size fits all bank process into a rich, varied ecosystem built around how people and businesses actually generate and manage money. Understanding the major branches of this industry, from peer to peer lending and buy now pay later to revenue based financing, embedded credit, and AI driven underwriting, helps borrowers find options that genuinely fit their situation and helps businesses recognize where real, responsible opportunity still exists in one of the most rapidly evolving corners of financial technology. The lenders and platforms that last will be the ones that use their new tools to extend credit more fairly and more transparently, not simply more quickly.
Share this article
Related Articles
Digital Payments Guide: Complete Overview for 2026
Everything you need to know about digital payments in 2026: how they work, every major type, key risks, and the trends reshaping how money moves.
What Is Fintech? A Complete Guide to Financial Technology in 2026
A complete 2026 guide to fintech, covering digital payments, banking, lending, blockchain, embedded finance, and the AI trends reshaping money.